Showing posts with label Development. Show all posts

Tuesday, January 22, 2013

Africa Rising - Kuna Siku Afika Itashindana Kiuchumi na Nchi za Magharibi

Afrika inajulikana kwa umaskini, lakini mwana uchumi Charles Robinson anatabiri kuwa kuna siku Afrika itashindana na nchi za Magharibi!  Kila kukicha tunasonga mbele!

*************************************
Kutoka CNN.com

Get ready for an Africa Boom


By Charles Robertson, Special to CNN

Editor’s note: Charles Robertson global chief economist for Renaissance Capital and lead author of ‘The Fastest Billion: The Story Behind Africa’s Economic Revolution.’ The views expressed are his own.

The rise of Africa’s long forlorn economies – what we at Renaissance Capital have dubbed “The Fastest Billion” – represents the final phase of a global economic transformation that began over 200 years ago as agrarian societies saddled with absolute rulers began their journey through industrialization into the pluralistic middle-class societies increasingly driven by the information age we know today.

For many reasons, Africa largely missed out on this journey. But no longer: while the process will not be complete by 2050, a changing set of global and local realities suggest that Africa is set to be the final beneficiary of this revolution.

Over the past decade, the billion people who live in Africa have experienced the fastest growth the continent has ever seen, and many of its countries (Nigeria, Ethiopia, Mozambique, Guinea) are among the fastest growing in the world. A growing body of evidence backs our view that as Africa’s population doubles to two billion over the next several decades, its GDP will increase from $2 trillion today to $29 trillion in today’s money by 2050.

To many in the West, such figures beggar belief – just as similar projections for East Asia’s Tiger economies or Latin America’s star performers did in the 1980s. The idea that Americans and Europeans would drive around in South Korean automobiles, or fly around in Brazilian-made jetliners, would have brought great guffaws from experts of 1980. But today, Hyundai, Kia and Embrear are household names. Things change quickly when certain tipping points are reached. We believe Africa has reached such a point.


More from GPS: How Africa could feed the world

By 2050, assuming a conservative trajectory similar to what India achieved since 1990, Africa will produce more GDP than the United States and eurozone combined do today, and its basic social, demographic and political realities will also be transformed. The necessary elements that have propelled countries from late medieval commerce with authoritarian government through to industrialized nations with comprehensive and far-reaching social and legal institutions are well known.

A continent rich in natural resources – mineral, agricultural and in energy – Africa is also rich in the youth of its population, enjoying a demographic advantage over all other regions of the world.

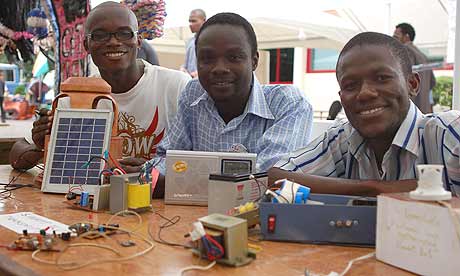
The pace of technological innovation globally is now so rapid, and technology is so easy to transfer – as evidenced by the boom in mobile phone technology and the roll-out of broadband across the continent – these young Africans are not only the recipients of technology, but via M-PESA banking, are becoming exporters of it, too.

Today, Africa has the greatest room to boom on the back of two centuries of global progress. The take-off in Africa began around the turn of the century, 40 years after independence. Why not earlier? Because human capital was extremely constrained by a lack of primary and secondary education, while global capital could find better opportunities in East Asia and Latin America. Political leaders in the 1960s and 1970s were inexperienced, often self-serving and were offered contradictory advice on how best to develop a country. There were no strong Asian role models to emulate. International involvement in Africa was too often geared towards Cold War geopolitics, feeding civil wars and strife, rather than trade and investment.

What has changed? Many governments have learnt from their mistakes and seen the positive reform examples not just in Asia, but more importantly in Africa itself, from Mauritius to Botswana and Cape Verde, and now Ghana to Rwanda. In most countries there has been no single reform miracle, like China’s in 1978 or India’s in 1991, but rather a series of small steps which taken together have been just as powerful.

Stronger growth and good public finances – Africa’s numbers are far better in this regard than those of Europe, the United States or Japan – have helped draw in record levels of foreign private-sector capital. But the improvement shows across the board – in primary and secondary education, in health, personal security, transparency and governance.

The headlines of the day may not support this – war rages in parts of Congo and Sudan, poverty and corruption stain too many of the continent’s peoples. Such are the stuff of headlines. But today we count around 30 democracies across the continent, some strong and immortal, but many fragile and still vulnerable. That number will grow.

Today the continent is reaping the benefits of high commodity prices and exports to China to begin the process of infrastructure investment that accelerates growth. Each year, in the oil sector alone, a major new discovery is heralded, from Ghana to Uganda and most recently Kenya, pushing Africa’s share of world oil reserves to 10 percent. African oil production growth has already been the fastest in the world over the past 10 years, all of it in sub-Saharan Africa (SSA). Africa now produces 10m barrels a day, as much as Russia or Saudi Arabia, with the 6m barrels of SSA alone worth $235 billion of oil revenue annually or 20% of 2011 GDP. Renaissance expects volume increases to ensure this tops $300 billion even with no change in oil prices by 2019.

Nearly a trillion dollars of oil revenue every three years means unprecedented inflows of foreign exchange to fund imports of investment and consumption goods. Rapid economic growth means growing African demand for resources. Do not be surprised if Nigerian steel consumption rises from 1.6 million tons annually today to 115 million tons annually by 2050. African motor vehicle sales of 8 million by 2020 may reach 14 million by 2030, higher than the U.S. today. Who knows – someday you may find yourself driving a Nigerian auto and dialing hands free on a Tanzanian-made phone. It has all happened before.
Monday, November 26, 2012

Nchi Maskini Duniani - Tanzania Imo!

TAARIFA KWA VYOMBO VYA HABARI


RIPOTI YA NCHI MASIKINI SANA DUNIANI MWAKA 2012

UKWELI WA MAMBO NA TARAKIMU

Geneva, 26 Novemba 2012 – Ripoti ya Nchi Maskini Sana Duniani ya Mwaka 20121, yenye kichwa kidogo cha habari Kutumia Fedha Zinazotumwa na Raia Wanaoishi Nga’ambo na Weledi Wao Kujenga Uwezo wa Uzalishaji, imetolewa leo.

Mwelekeo wa uhamiaji

 Idadi ya watu ambao wamehamia Ulaya kutoka Nchi Maskini Sana (LDCs) iliongezeka kutoka milioni 19 mwaka 2000 kufikia milioni 27 mwaka 2010. Hii ni sawa na 3.3% ya wakazi wote wa nchi hizo.

 Nchi Maskini Sana Duniani zinatoa 13% ya wahamiaji duniani kote---idadi ambayo inalingana na mgawo wa LDCs katika idadi ya wakazi wote duniani (12.1%).

 Wahamiaji wanne kati ya watano kutoka LDCs wanaishi kwenye nchi zinazoendelea (Kusini) na mmoja tu kati wa watano ndiye anaishi kwenye nchi zilizoendelea (Kaskazini).

Utumaji fedha

 Kiwango cha fedha zinazotumwa na raia waliohamia ng’ambo kwenda kwenye nchi zao kiliongezeka mara nane kati ya mwaka 1990 na 2011: Kutoka dola bilioni 3.5 kufikia dola bilioni 27. Tangu mwaka 2008 kiasi cha fedha kimeendelea kuongezeka pamoja na kuwepo na anguko la kiuchumi duniani.

 Mwaka 2011 kiasi cha fedha zilizotumwa kwenda nchini Tanzania kutoka Uingereza zilikuwa dola milioni 4.5, kutoka Canada dola milioni 3.2 na kutoka Kenya dola milioni 2.5.

 Mwaka 2011, fedha zilizotumwa kwenda LDCs zilikuwa kama mara mbili ya thamani ya uwekezaji wa moja kwa moja (FDI) katika nchi hizi (dola milioni 15), na kiwango hiki kilizidiwa tu na Misaada Rasmi Kutoka Nje, yaani ODA (dola bilioni 42 mwaka 2010), kama chanzo cha fedha kutoka nje ya nchi.

 Kiwango cha fedha zinazotumwa kutoka nje kama kingegawanywa kwa mwananchi mmoja mmoja kiliongezeka kutoka dola 10 kama kila mtu angepokea hadi dola 30 kati ya mwaka 2000 na 2010.

 Fedha zinazotumwa na raia wanaoishi nje zina umuhimu wa pekee kwa LDCs ikilinganishwa na nchi zilizo katika makundi mengine. Katika LDCs, fedha zinazotumwa na raia kutoka nje zinachangia 4.4% kwenye pato la nchi na 15% ya thamani ya bidhaa zinazouzwa nje. Kiwango hiki ni kikubwa kwa mara tatu ikilinganishwa na nchi nyingine zinazoendelea (ambazo siyo LDCs).

 Kuanzia mwaka 2008 hadi 2010, kiasi cha fedha kilichotumwa kutoka nga’mbo kinalingana na zaidi ya moja ya tano ya pato la taifa la nchi za Lesotho, Samoa, Haiti na Nepal.

 Tangu mwaka 2009 hadi 2011, nchi za Nepal na Haiti zilipata fedha nyingi za nje kutoka kwa raia wao walio ng’ambo kuliko zile ambazo nchi hizi zilipata kutokana na mauzo ya bidhaa nje.

 Kwa LDCs tisa, kiwango cha fedha zinazotumwa na raia wanaoishi nje kilizidi kile cha uwekezaji wa moja kwa moja kutoka nje (FDI) na misaada rasmi kutoka nje (ODA) kati ya mwaka 2008 na 2010. Hizi ni nchi za Bangladesh, Haiti, Lesotho, Nepal, Samoa, Senegal, Sudan, Togo na Yemen. Kwenye nchi nyingine nane za kundi la LDCs, katika kipindi hicho hicho, fedha zinazotumwa na raia kutoka ng’ambo zilizidi FDI: Benin, Burundi, Comoros, Ethiopia, Gambia, Guinea-Bissau, Kiribati na Uganda.

 Theluthi mbili ya fedha zinazotumwa na raia kutoka ng’ambo kwenda kwenye LDCs zinatoka kwenye nchi zinazoendelea.

 Duniani kote, gharama ya kutuma fedha zinafikia 9% ya kiwango cha fedha kilichotumwa; kwa LDCs gharama ni kubwa zaidi kwa theluthi moja (12%).

 Kama nchi zilizo kusini kwa Jangwa la Sahara zingelipia gharama za uhamishaji fedha kwa wastani wa gharama inayolipwa duniani kote, mapato yao yangekuwa yaliongezeka kwa dola bilioni 6 mwaka 2010.

 Asilimia 66 ya fedha zilizohamishwa kwenda kwenye LDCs kati ya mwaka 2009 na 2011 ni za nchi tatu tu: Bangladesh, Nepal na Sudan.

 Matumizi ya simu za mkono kwenye LDCs ni makubwa zaidi (368 kwa kila wakazi 1,000) kuliko idadi ya akaunti za benki (171 kwa wakazi 1,000). Simu za mkono zinaweza vile vile kutumika katika kuhamisha na kupokea fedha kutoka ng’ambo.

Kuhama kwa utaalam

 Mtu mmoja kati ya kila watu watatu wenye ujuzi mkubwa (mwenye elimu ya chuo kikuu) kutoka LDCs anaishi ng’ambo. Kwenye nchi zilizoendelea kiwango ni mtu mmoja katika kila watu 25.

 LDCs sita zina raia wao wataalaum wengi zaidi wanaoishi nje ya nchi kuliko wale waliobakia nchini mwao: Haiti, Samoa, Gambia, Tuvalu na Sierra Leone.

 Theluthi mbili ya wahamiaji wenye ujuzi mkubwa kutoka LDCs wanaishi kwenye nchi zilizoendelea; theluthi moja wanaishi katika nchi zinazoendelea.

 Kiwango cha kuhama kwa watu wenye ujuzi kwenda ng’ambo ni kikubwa (20% ) kwa LDCs nyingi (30 kati ya 48).

 Wahamiaji kutoka LDCs wenye elimu ya chuo kikuu ambao wanaishi na kufanya kazi ng’ambo inafikia milioni 2.

 Idadi ya Watanzania waliohamia Uingereza kwa kumbukumbu za mwaka 2000 ni 10,535.

 Aina ya wahamiaji inafuata ukubwa wa kipato wa nchi mwenyeji. Katika nchi zilizoendelea, 35% ya wahamiaji ni wale wenye elimu ya chuo kikuu; kwenye LDCs 4% tu ya wahamiaji wana kiwango hicho cha elimu. Viwango hivi ni kwa wahamiaji kutoka nchi zote, japo viwango ni hivi hivi kwa wahamiaji kutoka nchi za kundi la LDCs.

 Theluthi moja ya wahamiaji kutoka LDCs ambao wana elimu ya chuo kikuu wanaishi Marekani.

Uwezo wa kiuchumi (Uchumi mpana)

 Kiwango cha ukuaji wa uchumi kwa mwaka kwa LDCs tangu kipindi cha msukosuko wa kiuchumi duniani (2009-2011) ni 4.7%, ambacho ni chini ya kiwango cha kipindi cha miaka ya ukuaji mkubwa wa kiuchumi (2003-2008), yaani 7.9%. Hii ina maana kwamba kiwango cha ukuaji wa kipato kwa mwaka kwa kila mkazi kilishuka kutoka 5.4% miaka ya ukuaji mzuri wa uchumi hadi kufikia 2.4%.

 Wastani wa ukuaji halisi wa pato la nchi katika LDCs mwaka 2011, yaani 4.2%, ulikuwa chini ya 4.9% ya mwaka 2009 wakati wa anguko la uchumi duniani.

 Kile kinachojulikana kama Gross fixed capital formation kwenye LDCs kilipanda kidogo kutoka 20.7% ya pato la jumla la taifa mwaka katika miaka ya 2005-2007 kufikia 21.6% miaka ya 2008-2010. Hata hivyo, bado kilibaki chini ya viwango vya nchi nyingine zinazoendelea, ambazo zilifikia kiwango cha 30.1%.

 LDCs zinaendelea kutegemea sana raslimali kutoka nje. Pengo la pato linalotokana na uagizaji bidhaa na uuzaji bidhaa nje lilikuwa kubwa kwa 20% ya pato la jumla la taifa katika nchi tano za kundi la LDCs mwaka 2011, wakati LDCs nyingine 13 pengo lilikuwa asilimia 10 ya pato la jumla la taifa.

 Kiwango cha utegemezi wa rasilimali kutoka nje katika kulipia uwekezaji wa ndani ya nchi kati ya mwaka 2008 na 2010 kilikuwa 15% ya pato la jumla la taifa kwa LDCs ambazo hazisafirishi mafuta nje.

 Asilimia 62 ya mauzo ya bidhaa nje kutoka LDCs 48 yalikuwa ni kutoka nchi tano tu: Angola, Bangladesh, Equatorial Guinea, Yemen na Sudan. Ukiacha Bangladesh, nchi zote hizi zinauza mafuta nje.

 Mapato ya LDC kwa mauzo ya bidhaa nje yanategemea zaidi mauzo ya bidhaa moja (mafuta), ambayo yanaingiza 46% ya jumla ya mapato yote yanayotokana na mauzo ya bidhaa nje.

 Zaidi ya nusu ya mauzo ya nje kutoka LDCs (54%) yalikuwa yanakwenda kwenye nchi zinazoendelea mwaka 2011, mwelekeo unaothibitisha umuhimu wa biashara ya kusini-kusini. China ndiyo iliyonunua bidhaa nyingi zaidi kutoka LDCs (26.4%) ikiwazidi Jumuia ya Ulaya (20.4%) na Marekani (19%).


ZIKO WAPI NCHI MASKINI SANA DUNIANI?

Umoja wa Mataifa unaziweka nchi 48 kwenye kundi la Nchi Maskini Sana Duniani (LDCs). Mgawanyo wao ni kama ifuatavyo.


Africa (33): Angola, Benin, Burkina Faso, Burundi, Central African Republic, Chad, Comoros, Jamhuri ya KIdemnokrasia ya Kongo(DRC), Djibouti, Equatorial Guinea, Eritrea, Ethiopia, Gambia, Guinea, Guinea-Bissau, Lesotho, Liberia, Madagascar, Malawi, Mali, Mauritania, Msumbiji, Niger, Rwanda, Sao Tome na Principe, Senegal, Sierra Leone, Somalia, Sudan, Togo, Uganda, Jamhuri ya Muungano wa Tanzania na Zambia;

Asia (9): Afghanistan, Bangladesh, Bhutan, Cambodia, Lao, Myanmar, Nepal, Timor-Leste na Yemen;

Caribbean (1): Haiti;

Pacific (5): Kiribati, Samoa, Solomon Islands, Tuvalu na Vanuatu.


Mchoro 1 – Nchi 48 za kundi la LDCs

Imetolewa na UNCTAD

Kutengeneza list ya LDCs

LDCs inapitiwa upya kila baada ya miaka mitatu na Baraza la Uchumi na Jamii (ECOSOC) la Umoja wa Mataifa, kufuatana na mapendekezo ya kamati ya Sera ya Maendeleo (CDP).

Katika mapitio ya hivi karibuni, Machi 2012, CDP ilitumia vigezo vifuatavyo:

1. Kigezo cha pato la kila mtu, kwa kufuata Pato la Jumla la Nchi (GNI) kwa kila kichwa (wastani wa miaka mitatu)

2. Kigezo cha raslimali watu ambacho kinatumia viashiria kama lishe, afya, kuandikishwa shuleni na kujua kusoma na kuandika

3. Kigezo cha mazingira hatarishi ya kiuchumi. Ambacho kinatumia viashiria kama mishtuko ya kiasili, mishtuko ya kibiashara, udogo na umbali.

Nchi tatu tu zimefanikiwa kupanda daraja kutoka list ya nchi za kundi la LDCs: Botswana Desemba 1994, Cape Verde Desemba 2007 na Maldivs Januari 2011. Samoa inategemewa kupanda daraja tarehe 1 Januari 2014.

ECOSOC ilipitisha pendekezo la CDP kuipandisha daraja Equatiorial Guiones mwezi Julai mwaka 2009 na mwezi Julai 2012 ikakubali pendekezo la CDP kuipandisha Vanuatu. Hata hivyo ruhusa ya Baraza Kuu la Umoja wa Mataifa bado itahitajika ili kuzipandisha daraja nchi hizi mbili.